Affordable retirement plans for modern businesses
Choose the retirement plan that fits your business - with digital onboarding, payroll integrations, and ongoing compliance support included.
What you will get
- Potential employer tax credits
- Immediate vesting for employees
- Flexible employer contribution options
- Full payroll integration
- Employer & employee dashboards
- Automated contributions and rollovers
What you will get
- Potential employer tax credits
- Immediate vesting for employees
- Flexible employer contribution options
- Full payroll integration
- Employer & employee dashboards
- Automated contributions and rollovers
What you will get
- Contribute up to 25% of eligible compensation
- Higher contribution limit than SIMPLE IRA
- Flexible yearly contributions
- Easy setup & ongoing management
- Wide range of investment options
- Transfer existing retirement accounts
What you will get
- Contribute up to 25% of eligible compensation
- Higher contribution limit than SIMPLE IRA
- Flexible yearly contributions
- Easy setup & ongoing management
- Wide range of investment options
- Transfer existing retirement accounts
Simple IRAs built for small businesses that want better benefits
Offer a retirement plan that’s easy to manage, valuable to employees, and designed to grow with your business.
Give employees a benefit that supports their long-term financial future.
Claim tax credits that may offset most or all of your retirement plan setup costs over the first three years.
Make saving easier with contributions from every paycheck.
Meet WealthRabbit: Modern retirement plans made simple
Whether you're growing a business or working for yourself, WealthRabbit makes it easy to set up and manage retirement plans that fit your goals, budget, and future.
SIMPLE IRA
A flexible, low-maintenance retirement plan that helps business owners offer meaningful employee benefits without the complexity or high administrative costs.
What you’ll get
- Potential employer tax credits
- Easy setup with minimal paperwork
- Employee contributions with immediate vesting
- Flexible employer contribution options
SEP IRA
A powerful retirement savings option with higher contribution limits and simplified administration: ideal for solo business owners and independent professionals.
What you will get
- Higher annual contribution limits
- Tax-advantaged retirement savings
- Flexible yearly contributions
- Simple setup and ongoing management
Not sure which fits?
Answer a few simple questions and we’ll help guide you toward the retirement plan that may fit your business setup, goals, and team size.
Why Take the Quiz
- Takes under a minute
- No signup required
- Personalized recommendation
Your retirement plan
could pay for itself
Starting a retirement plan unlocks up to $16,500 in federal tax credits under SECURE 2.0, covering plan setup and administration costs for three years.
Credit amount depends on business size, employee count, and contribution structure. Talk to your tax advisor to confirm what your business qualifies for.
WealthRabbit vs. Other Providers
We built WealthRabbit for small businesses - not as an afterthought, but as the core product. See the difference.
We handle the retirement plan admin so you can focus on your business
From onboarding to compliance, WealthRabbit automates the busywork so managing your retirement plan stays simple from day one.
Fully digital setup
Launch your retirement plan in minutes with a streamlined, paperless onboarding experience.

Dedicated Employee Portal
Employees can securely enroll, manage their accounts, and track retirement savings anytime, anywhere.
Automated Compliance
We monitor contribution limits, required filings, and IRS rules automatically: helping you stay compliant with less manual work.

Simple Employer Dashboard
Manage contributions, employee enrollment, and plan activity from one easy-to-use dashboard.

Built to work with your payroll provider
Automatically sync payroll data to streamline contributions, reduce manual updates, and keep your retirement plan accurate and compliant.
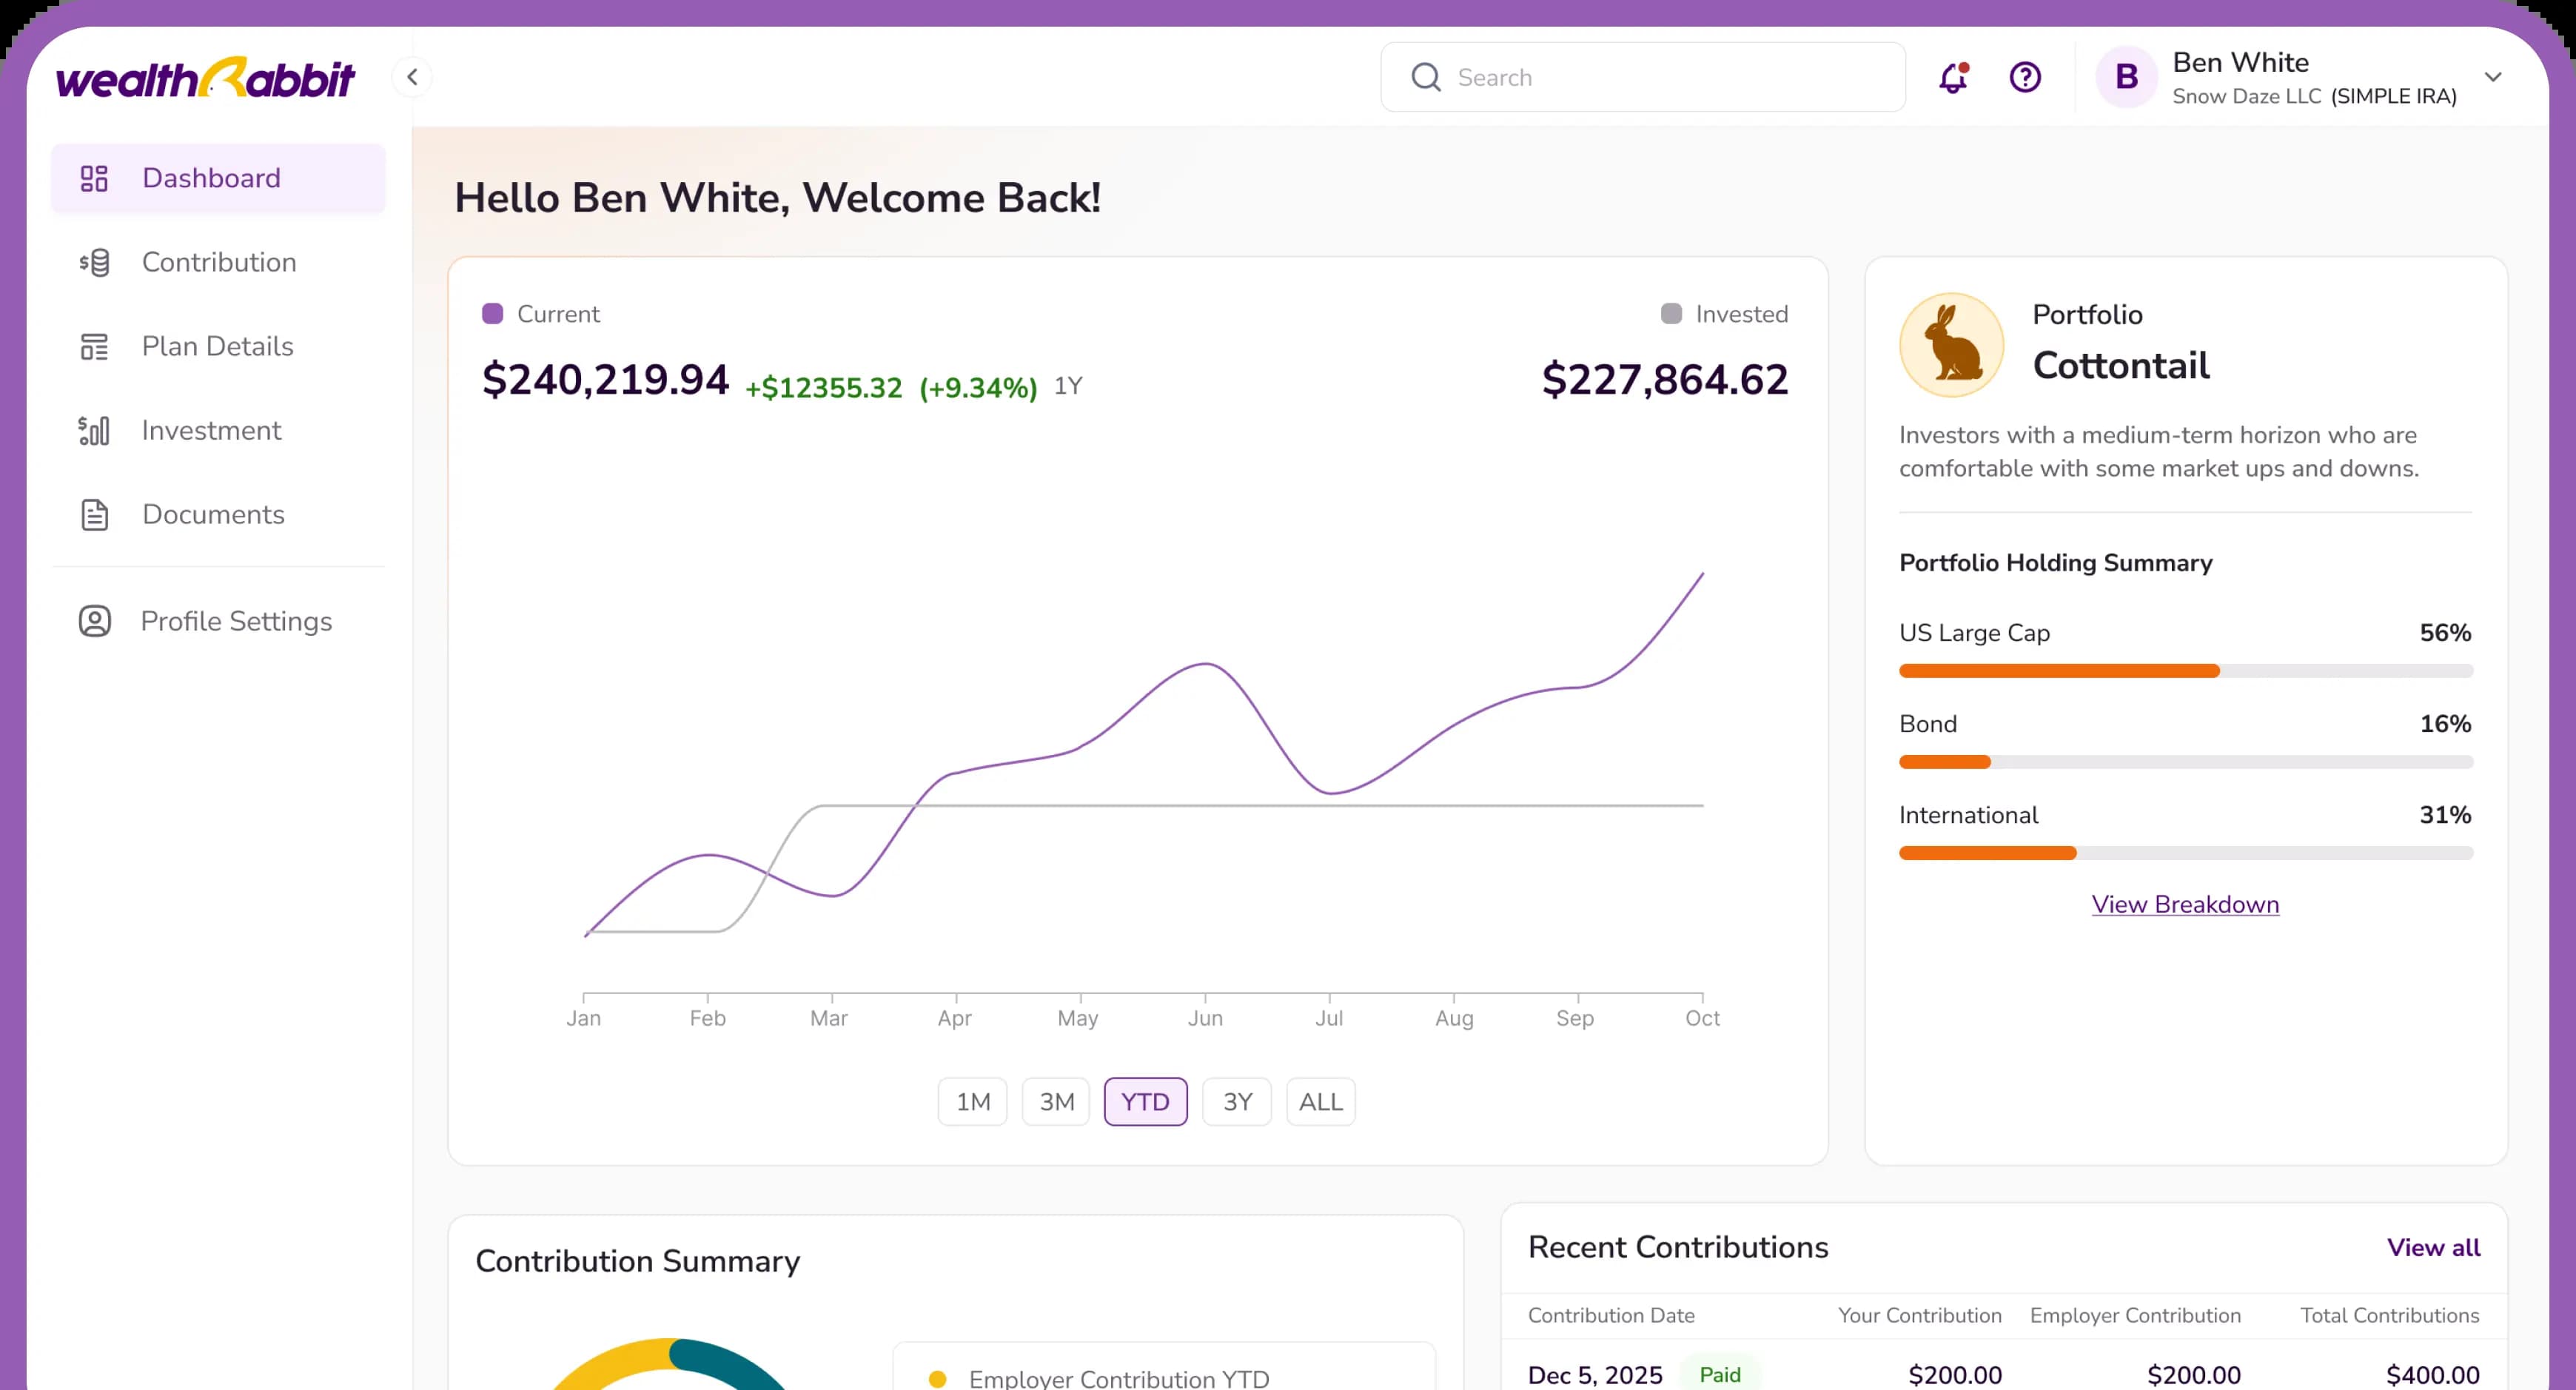
Your employees get a world-class portal too
Manage contributions and investments anytime, anywhere - whether on a computer or mobile device. View up-to-date data on contributions, investment performance, and account activity.
Launch your retirement
plan in minutes
Set up your plan, invite employees, and automate contributions, all from one streamlined digital platform.
1. Create your retirement plan
Choose the plan that fits your business and complete setup entirely online. No paperwork, printing, or faxing required.
2. Invite your employees
Send secure digital invitations so employees can enroll and manage their accounts on their own time.

3. Connect payroll & automate contributions
Sync payroll, schedule contributions, and let WealthRabbit automate deposits and ongoing administration.
Trusted by Businesses,
Accountants & Individuals
Small business owners, freelancers, and CPAs across the country rely on WealthRabbit for their team's retirement future.
Frequently asked questions
It depends on your team size, budget, and goals. A SIMPLE IRA suits businesses with up to 100 employees that want employees to contribute from their paychecks, with a required employer contribution. A SEP IRA suits owners who want to fund the plan themselves and contribute more, with no employee contributions. A 401(k) offers the highest limits and features but is more costly and complex to run.
Federal law does not require it. However, a growing number of states require employers without a plan to enroll employees in a state-run auto-IRA program. Offering your own plan, such as a SIMPLE IRA, SEP IRA, or 401(k), generally exempts you, although you may need to certify the exemption with your state. Requirements and employee thresholds vary by state.
SIMPLE IRA and SEP IRA plans are among the lowest-cost options because they have no annual IRS plan filings or nondiscrimination testing. Costs include any plan provider fees plus your own employer contributions. WealthRabbit charges a flat monthly fee, with a small per-employee fee for SIMPLE IRA plans, and eligible businesses may offset costs with tax credits.
Under SECURE 2.0, businesses with up to 50 employees can claim a credit for 100% of eligible startup costs, up to $5,000 per year for three years. Employers who contribute for employees earning $100,000 or less may also claim up to $1,000 per employee for up to five years, and there is a $500 auto-enrollment credit. Businesses with 51 to 100 employees qualify for reduced credits. Credits are claimed on Form 8881.
It depends on the plan. A SIMPLE IRA requires either a dollar-for-dollar match up to 3% of pay or a 2% contribution for every eligible employee. A SEP IRA contribution is optional each year, but if you contribute for yourself, you must contribute the same percentage for eligible employees. A 401(k) match is optional unless you choose a safe harbor design.
Yes. Self-employed owners and single-owner businesses can open a SEP IRA, a SIMPLE IRA, or a Solo 401(k). A SEP IRA is the simplest and allows the highest owner contribution at most income levels. A Solo 401(k) can allow more at lower income. If you plan to hire, a SIMPLE IRA or 401(k) may be easier to grow into.
You must follow your plan’s eligibility rules, deposit contributions on time, give eligible employees required notices, and make your employer contributions. SIMPLE IRA plans have an annual notice and election period, and SEP IRAs have a notice requirement when you adopt the plan. These plans typically have no annual Form 5500 filing or nondiscrimination testing.
When your payroll provider is connected to your retirement plan, each paycheck’s employee contribution is calculated, deducted, and sent to employee accounts automatically. This cuts manual entry and helps you meet deposit deadlines. SIMPLE IRA employee contributions must generally be deposited no later than 30 days after the end of the month in which they were withheld.
A SIMPLE IRA generally must be established by October 1 to take effect for that year, so setting one up now typically means a January 1, 2027 start. A new business that did not exist on October 1 may be able to start later. A SEP IRA can be set up and funded for the prior year until your tax filing deadline, including extensions.
Yes. Many businesses start with a SIMPLE IRA or SEP IRA and later move to a 401(k) as they grow. Timing matters: SIMPLE IRA plans are generally terminated at year-end, and there are rules for moving participant money during the first two years of participation. A plan provider or tax professional can help you plan the switch.
A business can offer a SIMPLE IRA if it has 100 or fewer employees who earned at least $1,000 in the prior year, and does not offer another retirement plan for those employees. If you grow past 100 employees, the plan can generally continue for two additional years as long as the rules are met.
You can create the plan online in minutes, then invite employees to join. Each employee enrolls on their own, choosing their contribution amount and investments, so your total timeline depends on how quickly they complete their steps. With WealthRabbit, you connect payroll to automate contributions, and the plan stays on track without ongoing manual work.