Colorado employers: Explore a SIMPLE IRA as an alternative to Colorado SecureSavings
Colorado employers with five or more employees and at least two years in business must either register for Colorado SecureSavings or offer a qualified retirement plan. If you want employer contributions and a choice of investment portfolios, a WealthRabbit SIMPLE IRA may be worth a look. Employers who offer a qualified plan certify their exemption with the state.
What is Colorado SecureSavings?
Colorado SecureSavings is Colorado’s state-run Roth IRA program for private-sector employees. If your business has five or more employees, has been in business for at least two years, and does not offer a qualified plan, you must register with the program or certify an exemption.

Registration deadlines (the original phase-in dates have passed)
- 50 or more employees: March 15, 2023
- 15 to 49 employees: May 15, 2023
- 5 to 14 employees: June 30, 2023
Employers that become eligible later must register when the program notifies them. If you have not registered or certified an exemption, doing so as soon as possible may help limit penalties.

Penalties for not complying
- Employers that do not comply may face penalties of up to $100 per eligible employee per year, up to $5,000 annually.
- The Colorado Department of the Treasury began sending pre-enforcement letters to non-compliant employers in August 2025.
Where Colorado SecureSavings may not be the right fit
Colorado SecureSavings is built to be simple, and for many small businesses that is exactly what they need. Here is what to weigh before you decide.
What it does well: no employer fees and no required employer contribution.
What it does not do:
- No employer contributionsYou cannot add a match or a profit share, so the plan cannot help you recruit or keep people.
- Roth IRA onlyEmployee savings are limited to Roth IRA contributions, up to $7,500 in 2027 ($8,600 if age 50 or older), subject to Roth income limits.
- A curated fund menuEmployees choose from state-selected funds rather than a broader portfolio menu.
- No plan to claim credits onBecause you are not sponsoring a plan, there are no startup costs to offset and no employer contributions to deduct.
A SIMPLE IRA: an alternative to consider
A SIMPLE IRA is an employer-sponsored plan for businesses with 100 or fewer employees. You decide how your team’s retirement benefit works, and your employees can save more each year than they could in a Colorado SecureSavings Roth IRA.
- Possible tax creditsEligible employers may claim a federal credit for plan startup costs for up to three years, plus a credit of up to $1,000 per employee for employer contributions in a plan’s early years. The amount depends on your size and your actual eligible costs.1
- Employer contributions that may be deductibleContributions you make are generally deductible as a business expense.
- Higher contribution limitsIn 2027, employees can defer up to $17,500 into a SIMPLE IRA, plus $4,000 more if they are 50 or older ($5,250 if 60 to 63).2
- A choice of investment portfoliosEmployees pick from WealthRabbit’s investment portfolios instead of a single state-selected menu. Investing involves risk, including loss of principal.
- A benefit people noticeAn employer contribution can help you recruit and keep good people.
Know before you choose:
A SIMPLE IRA is available to employers with 100 or fewer employees who earned $5,000 or more in the prior year. It must be the only retirement plan you offer that year. Employer contributions are required every year. A new SIMPLE IRA generally must start between January 1 and October 1; plans set up after October 1 generally begin the following January 1 (new businesses excepted). Withdrawals before age 59½ may be subject to a 10% additional tax, or 25% within the first two years of participation. Employers remain responsible for timely deposits and required notices.
See How Much You Can Save with a SIMPLE IRA
Small businesses can take advantage of tax credits to help cover setup and administrative costs. By launching a new plan with auto-enrollment, you could qualify for up to $5,500 in tax credits!
How tax credits work
Tax credits are designed to offset the cost of setting up and administering, as well as contributing to the employees retirement savings.
Employers can claim up to $5,000 per year for three years to offset plan setup and administrative costs. They may qualify for additional tax credits.
- Auto-enrollment bonusIf you make the plan automatic (employees are enrolled unless they opt out), you get an extra $500 credit for 3 years.
- Employer contributionsYou may also get credits for money you put into employees' accounts (up to $1,000 per employee in the early years).
Together, these credits can add up to thousands in savings for your business. Curious how much you could claim?
Try our calculator and see exactly how much you could save.
Estimate your tax credit
Disclosure*
The SIMPLE IRA tax credit calculator is intended to estimate the average tax credit for your business. Please note, it does not constitute tax or legal advice.
Set up a retirement plan your team will use
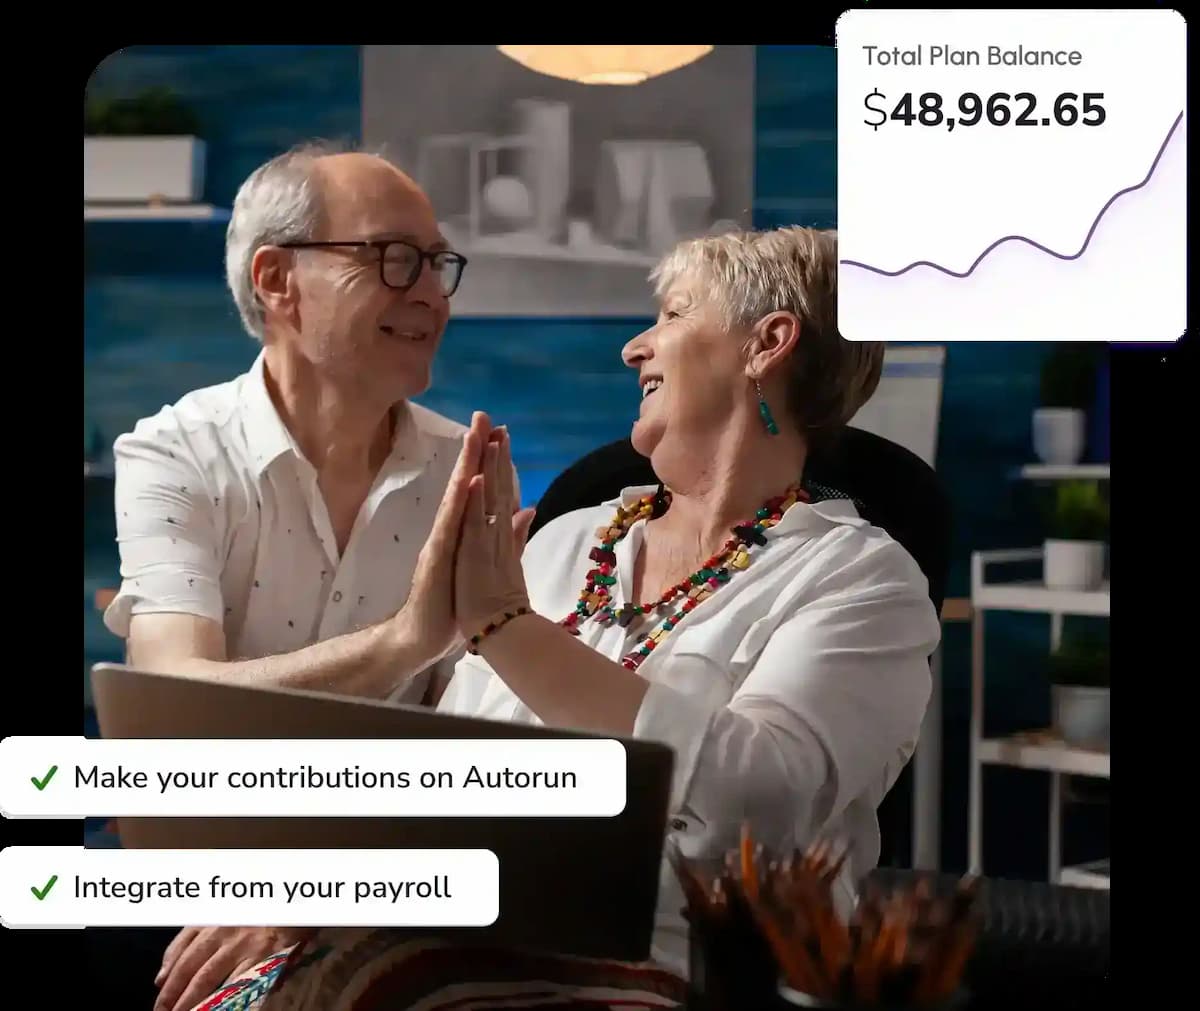
Hypothetical illustration for demonstration only. It is not an actual account and does not guarantee future results.
Instead of registering for Colorado SecureSavings, Colorado employers can offer a qualified plan such as a WealthRabbit SIMPLE IRA. Employers that offer a qualified plan are exempt from the state program but must certify their exemption with Colorado SecureSavings.
- Self-onboardingYou and your employees sign up online, and plan documents are e-signed in the app. Setup takes a few steps.
- Payroll integrationWealthRabbit connects with supported payroll systems to help you send contributions accurately and on time. You remain responsible for remitting contributions by the required deadlines.
- Plan rolloversMove funds from an existing retirement plan into WealthRabbit. Timing depends on your current provider. SIMPLE IRA rules apply: funds from non-SIMPLE plans can generally be rolled in only after two years of participation in the SIMPLE IRA.
- Automated contributionsSet up automatic deposits so contributions go out on schedule. You can review and change them at any time.
- Employer and employee portalsManage contributions and investments from your computer or phone, and see contributions, investment performance and account activity in one place.
Colorado SecureSavings vs. WealthRabbit SIMPLE IRA
A quick look at how the two options compare.
| Feature | Colorado SecureSavings | WealthRabbit SIMPLE IRA |
|---|---|---|
| Employer setup | Register, add your employees, and send contributions to the state program | Set up online with payroll sync. You manage contributions, notices and annual plan decisions |
| Employer cost | $0. Employees pay program fees | $29 per month plus $4 per employee per month, paid by the employer. Employee account fees also apply3 |
| Employer contributions | Not allowed | Required: match up to 3% of pay, or 2% of pay for every eligible employee |
| Account type | Roth IRA | SIMPLE IRA |
| 2027 employee limit | $7,500 ($8,600 if 50 or older) | $17,500, plus $4,000 if 50 or older ($5,250 if 60 to 63) |
| Investment menu | State-selected funds | WealthRabbit investment portfolios |
| Employee experience | State-run account and portal | WealthRabbit employer and employee portals and mobile app |
| Who can use it | Colorado employers with 5+ employees and 2+ years in business that don’t offer a plan | Employers with 100 or fewer employees; must be your only plan |
3 Colorado SecureSavings charges employers no fees. Participating employees pay the program’s fees. WealthRabbit SIMPLE IRA plan fees are paid by the employer: $29.00 per month plus $4.00 per employee per month. Employee accounts are also charged an annual fee of $10 plus an asset-based advisory fee of 0.20% to 0.50% (tiered). Additional fees and investment-related costs may apply. See our Fees and Services Disclosure and Form ADV Part 2A.
4 Information about Colorado SecureSavings is based on public information from the program and Colorado law as of October 21, 2026, and may change. WealthRabbit is not affiliated with, sponsored by, or endorsed by Colorado SecureSavings or the State of Colorado.
Frequently asked questions
Colorado SecureSavings is Colorado’s state-run Roth IRA program for private-sector employees whose employers do not offer a qualified retirement plan. Employers with five or more employees and at least two years in business must register, offer a qualified plan, or certify an exemption.
Eligible employers must either register or offer a qualified plan such as a SIMPLE IRA, SEP IRA or 401(k). Employers with fewer than five employees or less than two years in business are not required to participate. Employers that offer a qualified plan certify their exemption with the program.
The mandate was phased in by employer size in 2023. Those deadlines have passed. Employers that become eligible later must register when the program notifies them.
Employers that do not comply may face penalties of up to $100 per eligible employee per year, up to $5,000 annually.

Retirement planning that supports your success
Join hundreds of small businesses and individuals building real financial security with
WealthRabbit - fully digital, fully automated, fully yours.