Vermont Saves vs. WealthRabbit
Vermont employers: Explore a SIMPLE IRA as an alternative to Vermont Saves
Up to $17,500
Employee contribution
limit (2027)
Up to $16,500
SECURE 2.0 startup
tax credit (3 yrs)
<15 min
Average
setup time
100% Digital
No paperwork,
no fax, no hassle
Vermont’s retirement mandate is in effect
Vermont employers with two or more W-2 employees must register for Vermont Saves unless they offer a qualified plan, such as a SIMPLE IRA or 401(k). Exempt employers should certify through the Vermont Saves portal.
Registration deadlines by employer size (the dates below have passed)
25 or more employees
July 1, 2025
15 to 24 employees
January 1, 2026
2 to 14 employees
July 1, 2026
Fewer than 2 employees
Not currently required. Check vermontsaves.org for updates.
If you have not registered or certified an exemption, doing so as soon as possible may help limit penalties.
Penalties for not enrolling covered employees
Under Vermont law, the maximum penalty per covered employee, for each calendar year or part of a year, is:
For example, an employer with 10 covered employees that remains non-compliant after October 1, 2026 could face up to $750 in penalties. The Treasurer may waive penalties for employers that did not know of a failure and acted with reasonable diligence.
Your retirement plan
may help offset costs
Eligible Vermont employers may qualify for federal SECURE 2.0 tax credits when starting a SIMPLE IRA. The amount depends on your size, your eligible costs and your contributions.1
Assumptions and disclosures: Estimates are illustrative only, based on the information you enter and current federal rules. They are not a guarantee of any credit and are not tax advice. Consult your tax professional.
How a SIMPLE IRA compares to Vermont Saves
Vermont Saves is designed to provide a basic option. A SIMPLE IRA offers different features for employers and employees who want more.
Reasons Vermont businesses consider a SIMPLE IRA
Employer contributions
A SIMPLE IRA requires a 3% match or 2% non-elective contribution. Vermont Saves does not permit employer contributions.
Flexible investment options
Employees can choose from WealthRabbit’s professionally managed portfolios, from conservative to growth-oriented, including optional portfolios with crypto exposure managed with Bitwise. Investing involves risk, including loss of principal.
Higher contribution limits
In 2027, employees can defer up to $17,500 into a SIMPLE IRA ($19,100 for small employers that qualify), compared with the $7,500 Roth IRA limit in Vermont Saves.
Possible employer tax credits
Eligible employers may claim startup credits of up to $5,000 per year for the first three years, subject to eligibility.1
Set up your plan
in three steps
1. Create your plan
Sign up online and set up your SIMPLE IRA. Plan documents are e-signed in the app.
2. Invite your employees
Employees receive a secure invitation to set up their own account, choose their portfolio and contribution rate, or opt out.

3. Connect payroll and automate contributions
Sync your payroll system and schedule contributions. You remain responsible for timely deposits and required notices.
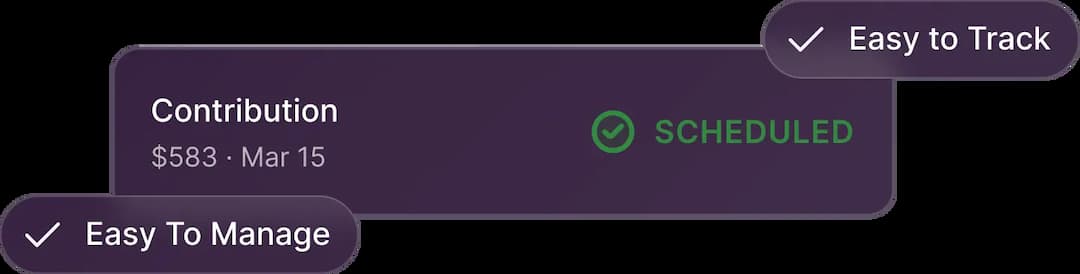
Tools for managing retirement benefits
Payroll integration
Connects with supported payroll systems to help automate deductions, employer matches and reporting.
Digital onboarding
Employees sign up on desktop or mobile.
Dashboards
View contributions, account balances and plan performance as an administrator or participant.
Compliance support
SIMPLE IRAs generally do not require Form 5500 filing. WealthRabbit provides plan records and reporting. WealthRabbit does not file taxes on your behalf.
Investment options
Employees answer 8 questions and receive a portfolio recommendation from the available managed portfolios.
Vermont mandate
A SIMPLE IRA is a qualified retirement plan. Employers that offer one are exempt from Vermont Saves but must certify their exemption through the state portal.
Professionally managed portfolios
Employees choose based on a simple 8-question risk assessment.
Core Portfolios
Diversified, time-tested investment strategies built for steady long-term growth and capital preservation.
- Professionally managed portfolios
- Time-tested methodologies
- Diversified asset allocation
- Automatic rebalancing for optimal performance
Crypto Portfolios
Powered by

For employees seeking additional diversification, select portfolios can include professionally managed crypto exposure powered by Bitwise.
- No wallets or direct custody management
- Integrated into diversified portfolios
- Professionally managed allocations
- Built using regulated ETFs & ETPs
SIMPLE IRA setup guides
Employee starter guide
- What a SIMPLE IRA is
- How enrollment works
- Employer contributions
- Investment options and account access
Employer setup guide
- Setup timeline
- Contribution rules and tax credit opportunities
- Requirements and deadlines
- Employee onboarding
Frequently asked questions
Vermont Saves is Vermont’s state-run Roth IRA program for private-sector employees whose employers do not offer a qualified retirement plan. It is sponsored by the Office of the Vermont State Treasurer. Employers with two or more W-2 employees must register or certify an exemption.
Covered Vermont employers must register unless they already offer a qualified retirement plan such as a SIMPLE IRA, SEP IRA or 401(k). Employers that offer a qualified plan should certify their exemption through the Vermont Saves portal. Employers are not charged to facilitate Vermont Saves.
Deadlines were phased in by employer size: July 1, 2025 (25 or more employees), January 1, 2026 (15 to 24) and July 1, 2026 (2 to 14). Those deadlines have passed.
The maximum penalty per covered employee not enrolled was $20 from October 1, 2025 to September 30, 2026, and is up to $75 on or after October 1, 2026. The Treasurer may waive penalties in certain cases.
Trusted by Businesses,
Accountants & Individuals
Small business owners, freelancers, and CPAs across the country rely on WealthRabbit for their team's retirement future.