Rhode Island employers: Explore a SIMPLE IRA as an alternative to RISavers
Rhode Island employers with five or more employees must either facilitate RISavers or offer a qualified retirement plan. If you want employer contributions and a choice of investment portfolios, a WealthRabbit SIMPLE IRA may be worth a look. Employers who offer a qualified plan certify their exemption with the state.
What is RISavers?
RISavers is Rhode Island’s state-run retirement program for private-sector employees whose employers don’t offer a qualified plan. Employers with five or more Rhode Island employees must facilitate it or certify an exemption, while smaller employers may join voluntarily. Eligible employees 18 or older with 120 days of employment are automatically enrolled in a Roth IRA unless they opt out. Employers send payroll contributions but can’t contribute themselves, and participants pay the program’s fees.

Compliance deadlines (phased by number of eligible employees)
- More than 100 eligible employees: October 15, 2026 (this date has passed)
- 50 to 99 eligible employees: October 15, 2027
- 5 to 49 eligible employees: October 15, 2028
The state describes the “new business registration” window that ended December 12, 2025 as an administrative onboarding milestone, not an enforcement deadline. You will be notified by RISavers when it is time to register. Your eligible-employee count is based on your average reported employees in the previous calendar year.

Penalties for not complying
Employers that do not comply with the state mandate may face financial penalties. Failing to remit employee deductions on time also violates Rhode Island law, and the state may impose penalties. Contact RISavers or the Rhode Island General Treasurer’s office for current enforcement details.
Where RISavers may not be the right fit
RISavers is built to be simple, and for many businesses that is exactly what they need. Here is what to weigh before you decide.
What it does well: minimal employer fees, no required employer contribution, and no fiduciary responsibility for you.
What it does not do:
- No employer contributionsYou cannot add a match or profit share, so the plan cannot help you recruit or keep people.
- Roth IRA onlyEmployee savings are limited to Roth IRA contributions, up to $7,500 in 2026 ($8,600 if age 50 or older), subject to Roth income limits.
- A set program designContribution options and investment choices are set by the state program.
- A curated fund menuEmployees choose from state-selected investments rather than a broader portfolio menu.
- No plan to claim credits onBecause you are not sponsoring a plan, there are no startup costs to offset and no employer contributions to deduct.
A SIMPLE IRA: an alternative to consider
A SIMPLE IRA is an employer-sponsored plan for businesses with 100 or fewer employees. You decide how your team’s retirement benefit works, and your employees can save more each year than they could in a RISavers Roth IRA.
- Possible tax creditsEligible employers may claim a federal credit for plan startup costs for up to three years, plus a credit of up to $1,000 per employee for employer contributions in a plan’s early years. The amount depends on your size and your actual eligible costs.1
- Employer contributions that may be deductibleContributions you make are generally deductible as a business expense.
- Higher contribution limitsIn 2026, employees can defer up to $17,000 into a SIMPLE IRA, plus $4,000 more if they are 50 or older ($5,250 if 60 to 63).2
- A choice of investment portfoliosEmployees pick from WealthRabbit’s investment portfolios instead of a single state-selected menu. Investing involves risk, including loss of principal.
- A benefit people noticeAn employer contribution can help you recruit and keep good people.
Know before you choose:
A SIMPLE IRA is available to employers with 100 or fewer employees who earned $5,000 or more in the prior year. It must be the only retirement plan you offer that year. Employer contributions are required every year: either a match of up to 3% of pay, or 2% of pay for every eligible employee. A new SIMPLE IRA generally must start between January 1 and October 1; plans set up after October 1 generally begin the following January 1 (new businesses excepted). Withdrawals before age 59½ may be subject to a 10% additional tax, or 25% within the first two years of participation. Employers remain responsible for timely deposits and required notices.
See How Much You Can Save with a SIMPLE IRA
Small businesses can take advantage of tax credits to help cover setup and administrative costs. By launching a new plan with auto-enrollment, you could qualify for up to $5,500 in tax credits!
How tax credits work
Tax credits are designed to offset the cost of setting up and administering, as well as contributing to the employees retirement savings.
Employers can claim up to $5,000 per year for three years to offset plan setup and administrative costs. They may qualify for additional tax credits.
- Auto-enrollment bonusIf you make the plan automatic (employees are enrolled unless they opt out), you get an extra $500 credit for 3 years.
- Employer contributionsYou may also get credits for money you put into employees' accounts (up to $1,000 per employee in the early years).
Together, these credits can add up to thousands in savings for your business. Curious how much you could claim?
Try our calculator and see exactly how much you could save.
Estimate your tax credit
Disclosure*
The SIMPLE IRA tax credit calculator is intended to estimate the average tax credit for your business. Please note, it does not constitute tax or legal advice.
Set up a retirement plan your team will use
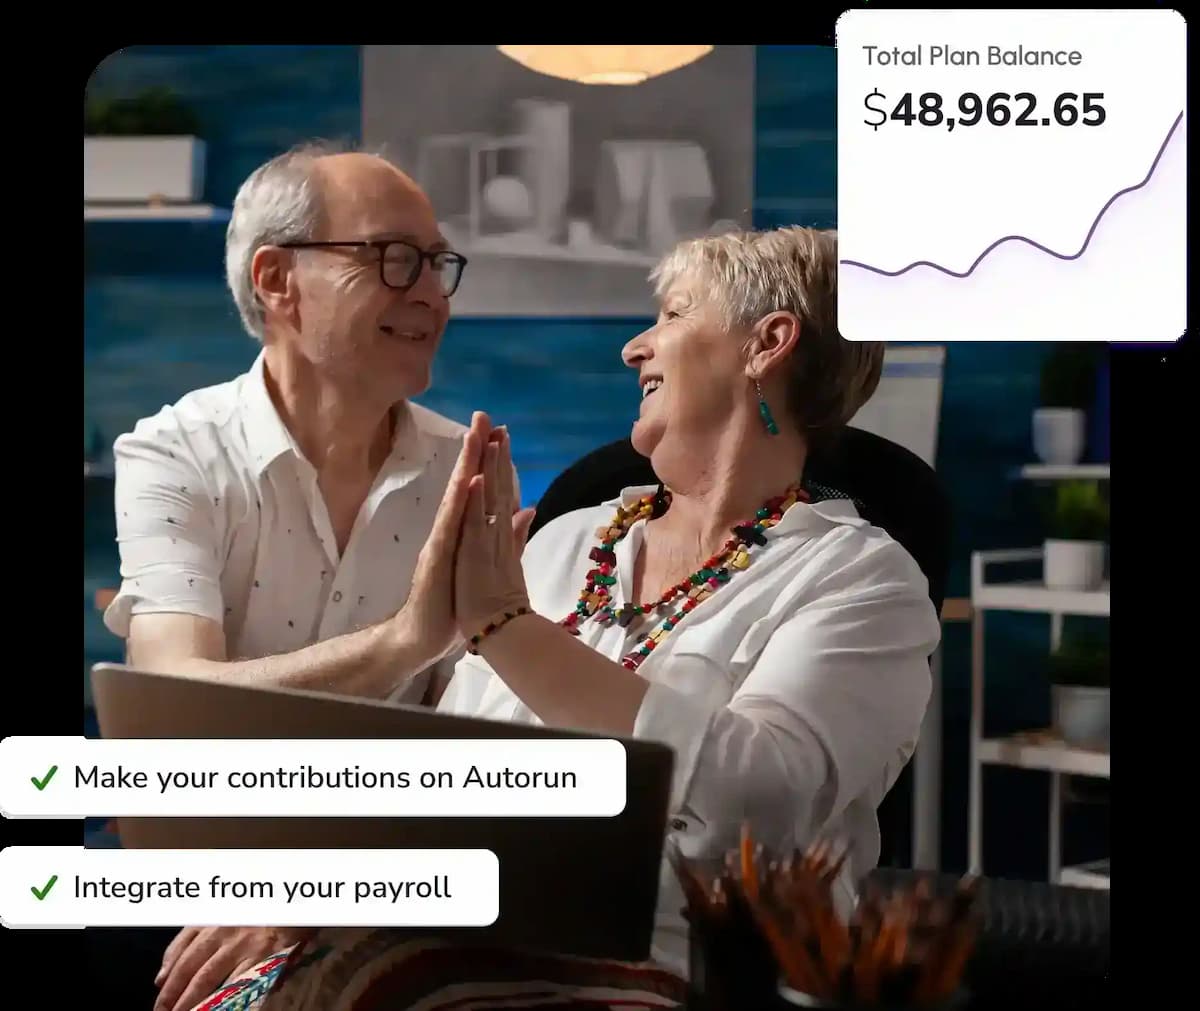
Hypothetical illustration for demonstration only. It is not an actual account and does not guarantee future results.
Instead of enrolling in RISavers, Rhode Island employers can offer a qualified plan such as a WealthRabbit SIMPLE IRA. Employers that offer a qualified plan are exempt from the state program but should certify their exemption using the access code provided by RISavers.
- Self-onboardingYou and your employees sign up online, and plan documents are e-signed in the app. Setup takes a few steps.
- Payroll integrationWealthRabbit connects with supported payroll systems to help you send contributions accurately and on time. You remain responsible for remitting contributions by the required deadlines.
- Plan rolloversMove funds from an existing retirement plan into WealthRabbit. Timing depends on your current provider. SIMPLE IRA rules apply: funds from non-SIMPLE plans can generally be rolled in only after two years of participation in the SIMPLE IRA.
- Automated contributionsSet up automatic deposits so contributions go out on schedule. You can review and change them at any time.
- Employer and employee portalsManage contributions and investments from your computer or phone, and see contributions, investment performance and account activity in one place.
RISavers vs. WealthRabbit SIMPLE IRA
A quick look at how the two options compare.
| Feature | RISavers | WealthRabbit SIMPLE IRA |
|---|---|---|
| Employer setup | State-run program. You register, add employees and send payroll contributions | Set up online with payroll sync. You manage contributions, notices and annual plan decisions |
| Account type | Roth IRA, no employer match | SIMPLE IRA with employer contributions |
| Who can use it | Rhode Island employers with 5+ employees that don’t offer a qualified plan. Employees must be 18+, employed 120+ days and earn taxable wages | Employers with 100 or fewer employees who earned $5,000+ in the prior year. Must be your only plan |
| Employer contributions | Not allowed | Required: match up to 3% of pay, or 2% of pay for every eligible employee |
| 2026 employee limit | $7,500 ($8,600 if 50 or older) | $17,000, plus $4,000 if 50 or older ($5,250 if 60 to 63) |
| Fees | Minimal employer fees. Participants pay program fees | $29 per month plus $4 per employee per month, paid by the employer. Employee account fees also apply |
| Investment menu | State-selected investments | WealthRabbit investment portfolios |
| Employee experience | State-run account and portal | WealthRabbit employer and employee portals and mobile app |
3 RISavers charges employers little to no fees. Participants pay the program’s fees. WealthRabbit SIMPLE IRA plan fees are paid by the employer: $29.00 per month plus $4.00 per employee per month. Employee accounts are also charged an annual fee of $10 plus an asset-based advisory fee of 0.20% to 0.50% (tiered). Additional fees and investment-related costs may apply. See our Fees and Services Disclosure and Form ADV Part 2A.
4 Information about RISavers is based on public information from the program and Rhode Island law as of October 21, 2026, and may change. WealthRabbit is not affiliated with, sponsored by, or endorsed by RISavers, the Rhode Island Office of the General Treasurer or the State of Rhode Island.
Frequently asked questions
RISavers is Rhode Island’s state-run Roth IRA program for private-sector employees whose employers do not offer a qualified retirement plan. Employers with five or more employees must facilitate the program or certify an exemption.
Private-sector employers (for-profit and nonprofit) with five or more employees in Rhode Island must facilitate RISavers unless they offer a qualified retirement plan. Employers with fewer than five employees may offer it but are not required to. Employers that offer a qualified plan, such as a SIMPLE IRA, should certify their exemption with RISavers.
Enforcement is phased in by number of eligible employees: October 15, 2026 for more than 100, October 15, 2027 for 50 to 99, and October 15, 2028 for 5 to 49. You will be notified by RISavers when it is time to register.
Employers that do not comply may face financial penalties, and failing to remit employee deductions on time violates Rhode Island law. Contact RISavers or the Rhode Island General Treasurer for current details.

Retirement planning that supports your success
Join hundreds of small businesses and individuals building real financial security with
WealthRabbit - fully digital, fully automated, fully yours.